Vesting is the process by which money your employer puts into your retirement plan becomes permanently yours. Until you are vested, some or all of those employer contributions can be taken back if you leave the job. Your own paycheck contributions, by contrast, are generally yours from the start.
Why vesting exists
Employers use vesting to reward people who stay. A match or profit-sharing contribution that vests over several years gives employees a reason to remain, and it lets the plan recover some costs when people leave early. Money that is not vested when someone departs is usually forfeited back to the plan, where it may be used to cover plan expenses or reduce future employer contributions, depending on the plan’s rules.
The two main types of schedules
Cliff vesting
Under a cliff schedule, you are 0% vested until you reach a set length of service, and then you jump to 100% all at once. Leave one day before the cliff and you could lose all employer contributions; stay past it and they are entirely yours.
Graded vesting
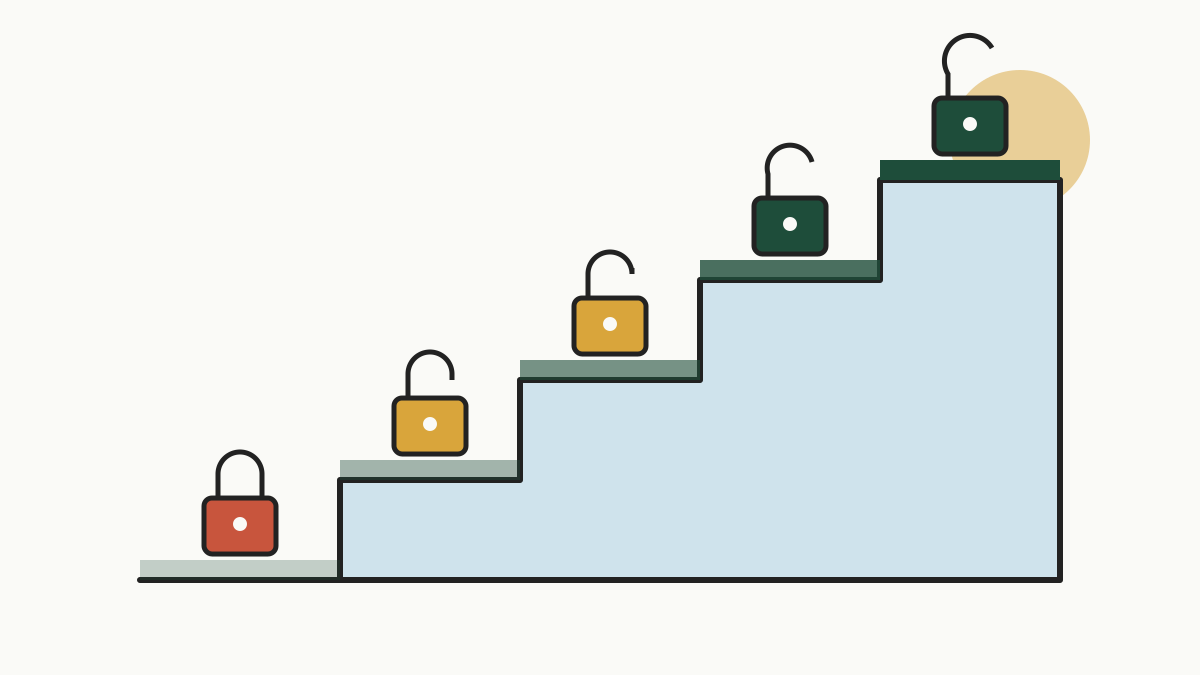
Under a graded schedule, ownership rises in steps. You might become 20% vested after one period of service, 40% after the next, and so on until you reach 100%. Leaving partway through means you keep the vested share and forfeit the rest.
Some plans use immediate vesting, meaning employer contributions are yours right away. Certain plan designs are required to vest immediately. Federal law sets maximum schedule lengths for many plan types, and those rules can change, so read your plan’s summary plan description for its exact terms rather than relying on general descriptions.
A worked example
The following is an illustration using a hypothetical graded schedule and round numbers. It is not taken from any specific plan or law.
| Years of service | Vested percentage |
|---|---|
| Less than 1 | 0% |
| 1 | 25% |
| 2 | 50% |
| 3 | 75% |
| 4 or more | 100% |
Suppose that after two and a half years, your account holds $12,000 of your own contributions and $8,000 of employer contributions, plus any growth credited to each. Under this schedule you are 50% vested. If you left now, you would keep all $12,000 of your money and $4,000 of the employer portion, for a total of $16,000. The other $4,000 would be forfeited.
If you stayed six more months and reached three years, you would be 75% vested, keeping $6,000 of the employer portion, assuming the balances stayed the same. That is $2,000 more than at two and a half years. Real balances move with the market, so actual amounts would differ.
Details worth checking
- How service is counted: some plans count calendar years, others count years with a minimum number of hours worked.
- Which contributions vest: matching and profit-sharing contributions may follow different schedules.
- Rehire rules: some plans restore prior service if you return within a certain time.
- Plan changes: if an employer ends or substantially changes a plan, affected participants may become fully vested under certain rules.
Common mistakes
- Looking at the total account balance and assuming all of it would go with you.
- Overlooking an upcoming vesting date when timing a job change.
- Assuming every employer uses the same schedule as a previous one.
- Confusing vesting with investment performance; vested money can still lose value, since investing involves risk.
Your plan statement or online account usually shows a vested balance separately from the total balance. Comparing those two figures, alongside the schedule in your plan documents, tells you exactly what you would keep if you left today and how that number would change over the coming months. It is a quick check that can make career decisions clearer.